A buyer touring a Federal-style house on Middle Street this summer asked the obvious question: will the city let me replace that roof? The listing agent had a ready answer, yes, with a Certificate of Approval from the Historic District Commission. What nobody mentioned, until the buyer's own insurance agent asked about the wiring, was that getting the city's blessing and getting an insurance company to write a policy are two entirely different processes, running on two entirely different clocks, and passing one tells you nothing about the other.
That gap is the thing worth understanding before you write an offer in Portsmouth's historic core. The design review most buyers brace for is real, but it is not the part of the transaction most likely to blow your budget or your timeline. The permit threshold is lower than people assume, and the insurance underwriting that follows has nothing to do with whether the commission approves your paint color.
The Line That Reclassifies Your Project
Portsmouth's building code draws a specific dollar figure around what counts as a routine repair. Ordinary repair work stays exempt from the permit process, until its cost, materials and labor combined, including the value of the owner's own labor, crosses $3,000. Cross that line and the job needs a building permit application reviewed by the Planning Department. If the work touches the exterior facade of a structure inside the Historic District, that permit also triggers Historic District Commission review, and the ordinance specifically calls out reroofing that changes the roof material as one of the triggers.
Three thousand dollars does not buy much roof, siding, or window work at current labor rates. A homeowner who thinks they are handling "a repair" can find themselves filing for a Certificate of Approval without having planned for the meeting, the timeline, or the materials guidance that comes with it.
There is a useful contrast buried in the same code. Interior renovations to a single-family dwelling bypass zoning review entirely, so a kitchen gut or a bathroom remodel that touches nothing visible from the street can move through the permit process faster than a simple reroofing job that happens to face Market Square. The exterior, not the scope, is what slows things down.
Which Streets Actually Trigger This
The Historic District itself is not one uniform zone. It runs roughly L-shaped from Market Square south to South Street and west to Madison and Columbia streets, covering more than 1,200 historically significant buildings, and it breaks into recognizable sub-areas that behave differently at the review table.
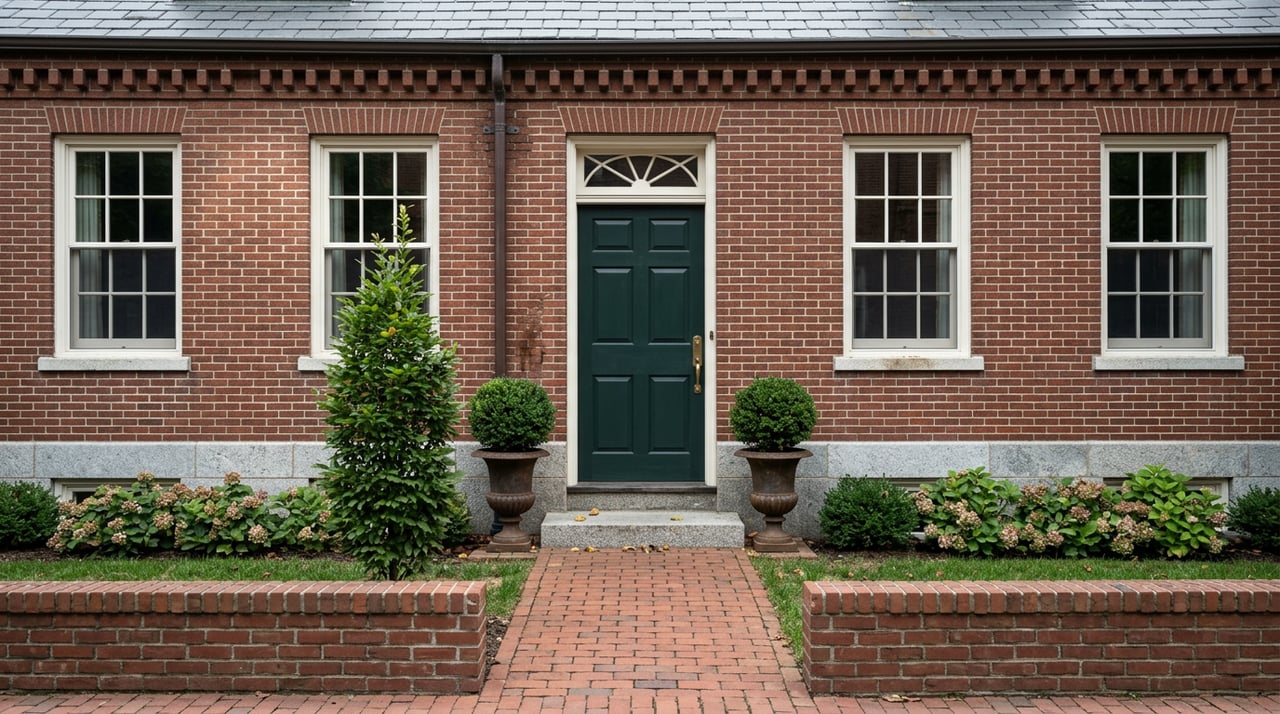
State and Middle Streets carry the most conspicuous stock, three-story Federal mansions on generous lots mixed with mid-19th-century Italianate and Mansard houses, the kind of street-facing detail the commission scrutinizes closely. The North End and Christian Shore wrap around North Mill Pond with a more residential mix. The South End holds the bulk of the city's older housing, consistent with downtown's median construction year of 1895. The West End, added to the district in 2010, covers the Islington Street corridor and carries a wider range of architectural styles, commercial and residential side by side, which tends to give owners there more flexibility than a Federal mansion on State Street.
This is not paperwork sitting dormant in an archive. The commission's own meeting record this year shows active cases at named addresses: Certificate of Approval hearings for 325 Marcy Street, 129 State Street, and 1 Congress Street, a work session on a proposed demolition and multi-family replacement at 58 Humphrey's Court, and a one-year extension request tied to 84 Pleasant Street. The commission has also been redrawing its own map this year, with draft boundary line changes for Middle Street still under discussion as of this summer. A buyer who assumes district boundaries are fixed and unchanging is working from an outdated picture.
The city also maintains a separate National Register listing for the Downtown Historic District, added in 2017 as mitigation tied to the Memorial Bridge replacement project. That designation is honorary and distinct from the local Historic District that actually governs what you can do to your exterior. A property can carry National Register status without answering to the local commission at all, and the reverse is also true. Confirming which designation, or both, applies to a specific parcel is not something a buyer should guess at from a listing description.
The Second Clock: Your Insurer Isn't Reading the City's Calendar
Here is where the real cost surprises live. Getting HDC approval says nothing about whether an insurance company will write you a policy, because underwriters are evaluating a completely different set of risks on their own timeline.
Knob-and-tube wiring is the most common trip wire. Many homes built before 1950 still carry some of it, and standard carriers frequently decline to write coverage at all until it is replaced. A full rewire of a typical historic-sized home runs somewhere between $15,000 and $30,000, a number that has nothing to do with whether your roof material passed HDC review and everything to do with whether you can close on schedule.
Foundations tell a similar story. A meaningful share of Portsmouth's pre-1900 housing sits on original granite or fieldstone foundations, durable but prone to settling over more than a century, and a structural engineer's assessment, typically $400 to $800, is the kind of due diligence that belongs inside your inspection window rather than after closing.
Not every carrier treats these homes the same way. Insurers that specialize in high-value and historic properties, among them Chubb, PURE, and Cincinnati Insurance, tend to underwrite period construction with more nuance than a standard homeowners policy allows, because their process assumes the cost of period-accurate materials rather than a generic replacement estimate. PURE, notably, sends engineers to inspect a property and flag vulnerabilities before binding coverage, which is useful information but also adds a step to your timeline that a buyer moving through a 30 or 45 day closing needs to account for.
The mistake is treating HDC approval as the finish line. It is one gate. Insurability is the other, and it does not care what color your siding is.
What to Verify Before Your Contingency Period Closes
A buyer serious about a historic Portsmouth property has a short list of things worth confirming before the inspection contingency runs out, not after.
- Confirm the parcel's actual district status through city records rather than the listing description. Age alone does not put a house inside the regulated Historic District, and boundary lines have moved before.
- Pull the permit history on the property. The city will not issue a new permit while an existing one remains open and uninspected, so an unresolved permit from a prior owner becomes your problem the moment you close.
- Have an electrician who specializes in older homes evaluate the wiring specifically, separate from your general home inspector. What kind of wiring is present, and how much of it, determines your entire insurance conversation.
- Request real, property-specific insurance quotes during your inspection window, not after your financing is locked. Ask directly whether the carrier writes policies with partial knob-and-tube, and what condition they require first.
- If the foundation is stone or granite, budget for a structural engineer's assessment as part of your due diligence, not as an optional extra.
- If you are planning any exterior work after closing, price it against the $3,000 threshold before you make an offer, so you know in advance whether you are buying a house or buying a house plus a Certificate of Approval process.
A Few Questions Worth Settling Early
Does every old house in Portsmouth need Historic District Commission approval? No. Only properties inside the mapped Historic District boundary answer to the commission, and age by itself does not establish that status. Two houses built four years apart can sit on opposite sides of that line.
Can I still finance a home with knob-and-tube wiring? Financing is usually the easier half. Insurance is where buyers get stuck, since many standard carriers decline outright and the specialty carriers that will write a policy often want documentation or upgrades first.
How much lead time should I plan for HDC review? The commission generally meets the first Wednesday of each month, occasionally adding a second Wednesday when the docket is heavy. City rules also note that an application is considered abandoned after a year without progress, so plan your renovation timeline with real margin rather than assuming a single meeting settles everything.
A historic Portsmouth address rewards patience and specific homework. If you are weighing a property in the South End, the West End, or anywhere inside those district lines, Cheryl Zarella and her team can walk the parcel history, the permit record, and the insurance conversation with you before your contingency clock starts running. Request a complimentary home valuation to start that conversation on the right footing.